Centralized No More: The True Price Mega-Factories Pay for Consolidation
Photo: European Southern Observatory, CC BY 4.0, via Wikimedia Commons
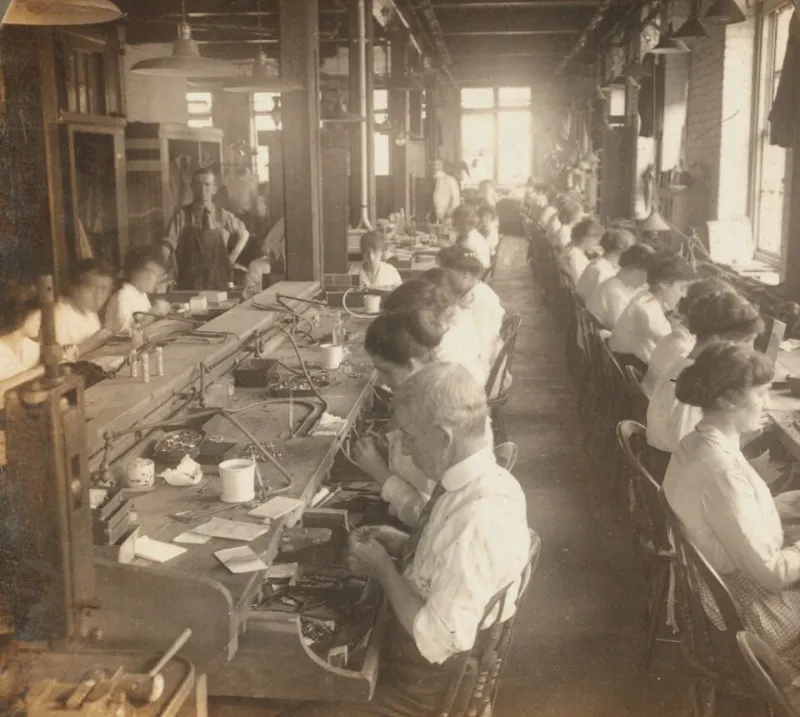
For most of the twentieth century, the logic of industrial consolidation was essentially unquestioned. Bigger factories meant lower per-unit costs, and lower per-unit costs meant market dominance. The mega-factory became a monument to that logic—vast, vertically integrated, and engineered for maximum throughput at a single geographic point. What that model obscured, however, was a parallel ledger of costs that rarely appeared on a standard income statement. Today, as distributed micro-manufacturing networks mature into credible enterprise-grade alternatives, that hidden ledger is finally being opened.
The Illusion of Economies of Scale
Conventional cost accounting tends to reward consolidation. When overhead is spread across millions of units, the numbers look compelling. What those calculations routinely omit are the systemic costs that accumulate precisely because of scale: the carrying costs of enormous raw-material inventories, the transportation expenditures required to move finished goods from a single production hub to dispersed end markets, and the organizational complexity that grows geometrically as a facility expands.
Perhaps more consequentially, mega-factories are engineered for stability, not adaptability. Retooling a 500,000-square-foot production floor to accommodate a new product variant is a months-long undertaking that consumes capital and management bandwidth. In markets where product life cycles are measured in quarters rather than years, that inflexibility carries a real economic penalty—one that rarely surfaces in a facility's cost-per-unit metrics but shows up unmistakably in lost revenue and ceded market share.
Supply Chain Concentration as Structural Risk
The events of 2020 and 2021 provided a brutal education in what risk managers had long been underweighting: geographic concentration of production is a single point of failure at industrial scale. When a mega-factory located in a single region faces a port closure, a natural disaster, a labor disruption, or a regulatory shift, the entire supply commitment of an enterprise can be suspended simultaneously. The downstream consequences—customer defections, contractual penalties, emergency air-freight expenditures—are rarely captured in pre-disruption cost models.
Distributed micro-manufacturing networks invert this vulnerability. By dispersing production nodes across multiple regions, enterprises introduce structural redundancy that functions as an operational insurance policy. If one node is compromised, adjacent facilities absorb the shortfall. The network continues to produce. This architecture does not merely reduce risk in theory; companies that transitioned to distributed models during the supply disruptions of the early 2020s documented measurably superior on-time delivery rates compared to competitors still operating from centralized campuses.
One Midwest-based industrial components manufacturer, for example, restructured its production footprint from two large centralized plants into a network of seven regional micro-facilities between 2021 and 2023. The transition initially raised per-unit fixed costs by a modest margin. Within eighteen months, however, the company reported a 34 percent reduction in logistics expenditure, a 22 percent improvement in order-to-ship lead times, and, critically, zero production shutdowns during a period when several of its centralized competitors experienced significant disruptions.
Time-to-Market as a Competitive Currency
Speed is increasingly the dimension on which industrial enterprises differentiate. Customers across sectors—from automotive to medical devices to consumer electronics—are compressing their own product development cycles and expecting their manufacturing partners to match that pace. A mega-factory optimized for long production runs and stable SKU portfolios is structurally misaligned with this expectation.
Micro-manufacturing facilities, by contrast, are designed from the ground up for reconfigurability. Smaller floor plates, modular equipment arrangements, and leaner workforce structures allow these operations to pivot from one production configuration to another in days rather than months. When a customer requires a design modification or an accelerated delivery schedule, a distributed network can respond at the node closest to the customer's facility, further compressing lead times.
This proximity advantage extends beyond speed. Locating production closer to end markets reduces the working capital tied up in in-transit inventory, lowers the carbon footprint of finished-goods logistics, and enables tighter quality feedback loops between production and the customer's engineering teams. These are not marginal improvements; they represent a fundamentally different value proposition that centralized models cannot replicate without dismantling the very consolidation that defines them.
Rethinking the Total Cost of Ownership
The case for distributed micro-manufacturing ultimately rests on a more complete accounting framework than the one that sustained the mega-factory era. When enterprises calculate the total cost of ownership for their production footprint—incorporating supply chain risk, logistics expenditure, inventory carrying costs, time-to-market penalties, and the organizational drag of managing monolithic facilities—the apparent cost advantage of consolidation frequently inverts.
This is not an argument that centralized production is categorically obsolete. For certain commodity products with stable demand profiles and long production horizons, large-scale facilities retain legitimate economic rationale. The critical insight is that the universe of products and markets for which that rationale holds is shrinking, while the universe of applications where distributed micro-manufacturing delivers superior total economics is expanding.
Enterprises that recognize this shift early are not simply reducing costs. They are restructuring their manufacturing footprint in ways that are inherently more responsive, more resilient, and more aligned with the velocity at which modern markets operate. The hidden costs of scale are no longer hidden. The question for industrial leaders is whether they will act on that knowledge before their competitors do.